Additional Links
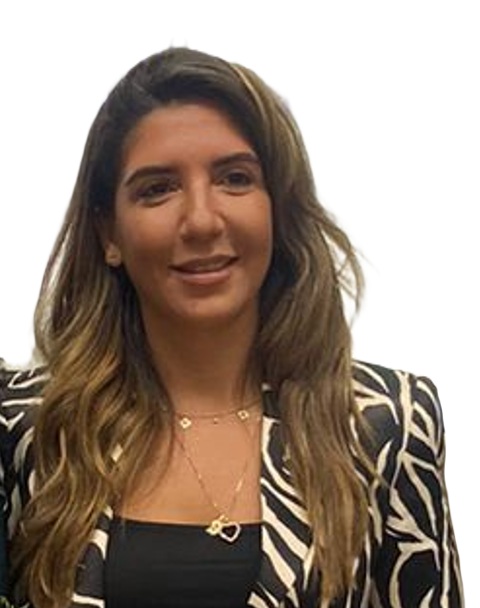
Rim Chérif
- Position: Assistant Professor, Finance
- Department: Heikal Department of Management
- Email: rim.cherif@aucegypt.edu
Rim Chérif is an assistant professor of finance at the Onsi Sawiris School of Business, The American University in Cairo, where she also serves as academic advisor for the Master of Science in finance. She holds a PhD in financial engineering from HEC Montréal, where her dissertation, supervised by Hatem Ben-Ameur and Bruno Rémillard, focused on pricing complex derivative securities under Lévy processes.
Her research develops computational and statistical methods for derivatives pricing, credit risk and sustainable finance. It has appeared in journals including Quantitative Finance, the Journal of Futures Markets and the Journal of Derivatives. A recipient of the AUC Teaching Award, she has supervised numerous graduate theses and has collaborated with industry on consulting projects. She serves on the scientific committee of the AfriMed Finance Society. Outside academia, she enjoys traveling and painting, and she has led initiatives supporting children without family care.
- Computational methods for derivatives and corporate securities: dynamic programming, least-squares Monte Carlo and parallel computing under Lévy and jump-diffusion dynamics.
- Credit risk and dependence modeling: structural models and their quasi-maximum-likelihood estimation, distance to default and flexible copulas for sovereign CDS markets.
- Climate and sustainable finance: green bond pricing, carbon risk in financial institutions, weather derivatives and real options for the circular economy.
- Recognition in Research, School of Business, The American University in Cairo, 2026
- Excellence in Teaching Award, School of Business, The American University in Cairo, 2023
- PhD in financial engineering, HEC Montréal (Canada), 2017